 Weather
 Locations
 Careers
 Login


Wine grape updates
Wine grape production declines.
Wine markets remain relatively weak. NielsenIQ reported U.S. year-over-year wine sales declined 2.8% by value and 4.7% by volume as of mid-September. Excess inventory levels, weak consumer demand, and growing pressure on mid-sized wineries remain the primary headwinds. Despite these challenges, operators with strong direct-to-consumer programs, wine clubs, premium brands, and differentiated customer experiences continue to outperform the broader market. Smaller wineries with strong marketing and loyal customer bases appear to be navigating the downturn more successfully than those reliant on distribution or tasting room traffic alone. Industry consolidation continued in September 2026 with increased acquisitions of wine brands, inventories, and intellectual property.
Wine grape harvest is progressing across the West Coast and year-over-year production declines are expected. This decline is due to a combination of reduced and/or idled acres, efforts to realign supply with demand, weather-related impacts, and smoke taint in Oregon and Washington. Powdery mildew has also been observed in the Willamette Valley. California yields vary by location, with some growers reporting declines ranging from 20%-60%. Washington’s crop is likely to fall 5%-10% from the previous season. Grape demand remains weak and prices remain under pressure. Profitability increasingly depends on flexibility, production efficiency, strong winery relationships, and growing varieties aligned with current consumer preferences, particularly white wines.
Profitability
September 16, 2026Wine: Slightly unprofitable - Neutral 12-month outlook
Wine grapes: Unprofitable - Neutral 12-month outlook
Wine demand continues to soften and pressure the industry, particularly in the lower- to mid-range segments.
Weak demand and excess bulk wine inventories continue to pressure wine grape producers.
The U.S. is the fourth largest New World (non-European) producer globally, it is the largest consumer, importing a third of its domestic supply. Key foreign suppliers include Italy, Canada, France, Australia, Chile and New Zealand. The U.S. exports 8% of its production, with about 50% split between the United Kingdom and Canada.
Wine production, exports and imports
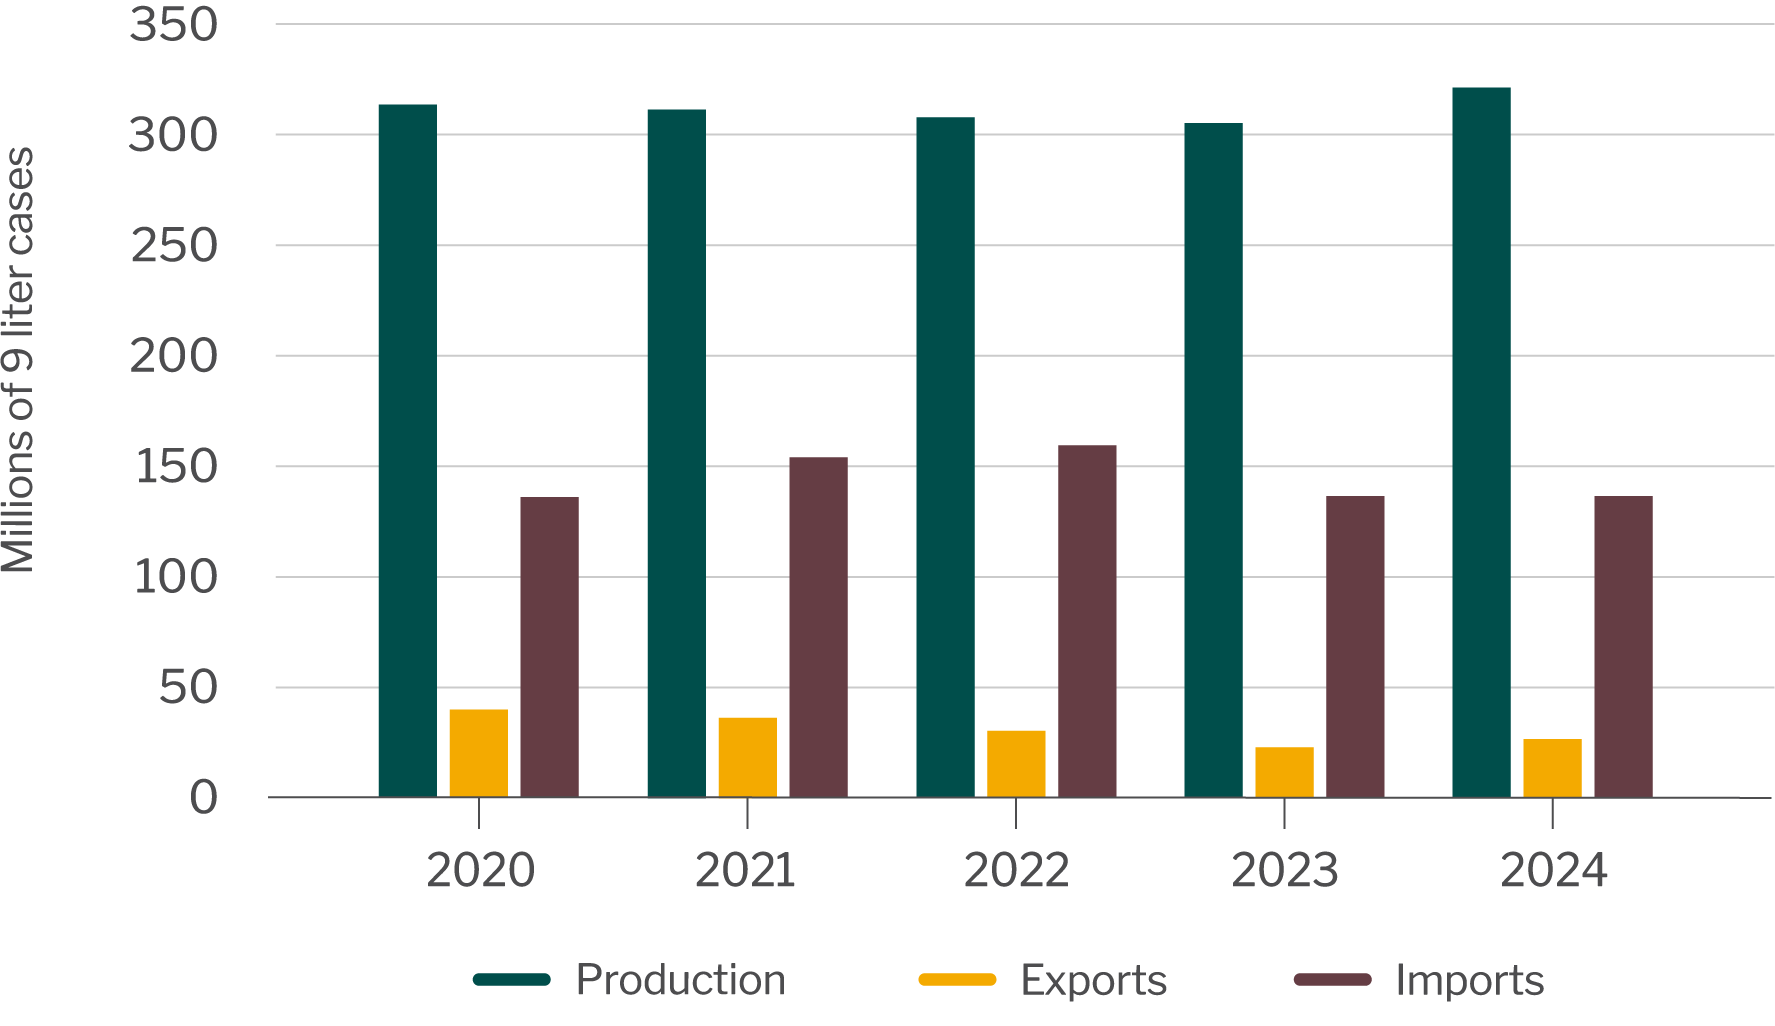
Source: Wine Institute. U.S. Census Bureau.
Tariff tracker - Tariff rates applied to U.S. trade partners are consistenly updated to reflect policy changes. The World Trade Organization (WTO) tracks duties and tariffs on wine. For your convenience, the following link will take you to tariff data for the United Kingdom. Wine is currently exempt from tariffs for Canada under the United States-Mexico-Canada Agreement (USMCA), but please refer to the U.S. Trade Representative website for up-to-date information. WTO also tracks rates for wine imports to the U.S. Please consult with a trade lawyer or professional for detailed and up-to-date insights on tariff rates and their application to wine.
For guidance on interpreting duty and tariff rates, please refer to our Tariff Guide.
Wine grape updates
Wine grape production declines.
Wine markets remain relatively weak. NielsenIQ reported U.S. year-over-year wine sales declined 2.8% by value and 4.7% by volume as of mid-September. Excess inventory levels, weak consumer demand, and growing pressure on mid-sized wineries remain the primary headwinds. Despite these challenges, operators with strong direct-to-consumer programs, wine clubs, premium brands, and differentiated customer experiences continue to outperform the broader market. Smaller wineries with strong marketing and loyal customer bases appear to be navigating the downturn more successfully than those reliant on distribution or tasting room traffic alone. Industry consolidation continued in September 2026 with increased acquisitions of wine brands, inventories, and intellectual property.
Wine grape harvest is progressing across the West Coast and year-over-year production declines are expected. This decline is due to a combination of reduced and/or idled acres, efforts to realign supply with demand, weather-related impacts, and smoke taint in Oregon and Washington. Powdery mildew has also been observed in the Willamette Valley. California yields vary by location, with some growers reporting declines ranging from 20%-60%. Washington’s crop is likely to fall 5%-10% from the previous season. Grape demand remains weak and prices remain under pressure. Profitability increasingly depends on flexibility, production efficiency, strong winery relationships, and growing varieties aligned with current consumer preferences, particularly white wines.

Profitability
September 16, 2026Wine: Slightly unprofitable - Neutral 12-month outlook
Wine grapes: Unprofitable - Neutral 12-month outlook
Wine demand continues to soften and pressure the industry, particularly in the lower- to mid-range segments.
Weak demand and excess bulk wine inventories continue to pressure wine grape producers.
The U.S. is the fourth largest New World (non-European) producer globally, it is the largest consumer, importing a third of its domestic supply. Key foreign suppliers include Italy, Canada, France, Australia, Chile and New Zealand. The U.S. exports 8% of its production, with about 50% split between the United Kingdom and Canada.
Wine production, exports and imports
Source: Wine Institute. U.S. Census Bureau.
Tariff tracker - Tariff rates applied to U.S. trade partners are consistenly updated to reflect policy changes. The World Trade Organization (WTO) tracks duties and tariffs on wine. For your convenience, the following link will take you to tariff data for the United Kingdom. Wine is currently exempt from tariffs for Canada under the United States-Mexico-Canada Agreement (USMCA), but please refer to the U.S. Trade Representative website for up-to-date information. WTO also tracks rates for wine imports to the U.S. Please consult with a trade lawyer or professional for detailed and up-to-date insights on tariff rates and their application to wine.
For guidance on interpreting duty and tariff rates, please refer to our Tariff Guide.
IN THIS SECTION


Wine/Vineyard Industry Perspective
View the latest AgWest Wine/Vineyard Industry Perspective
Learn more